
What to do first when a casino asks for ID before a withdrawal
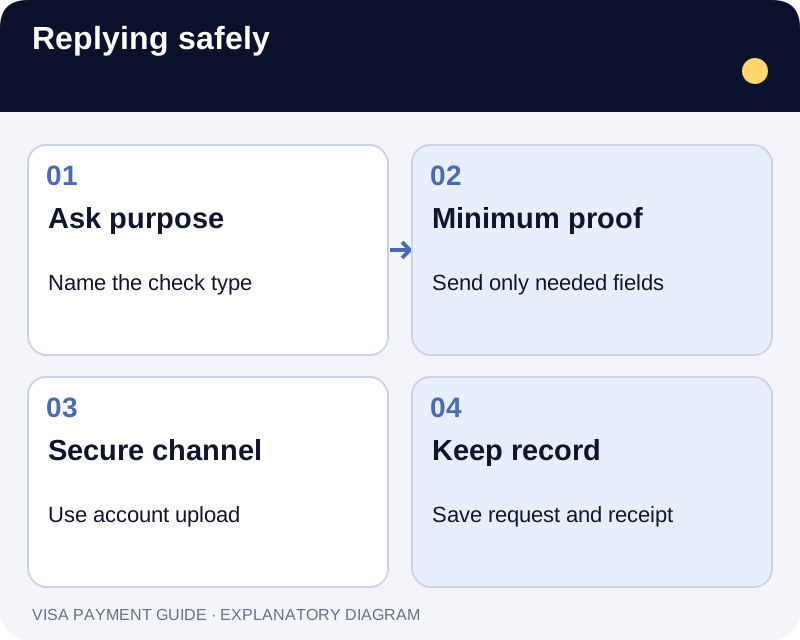
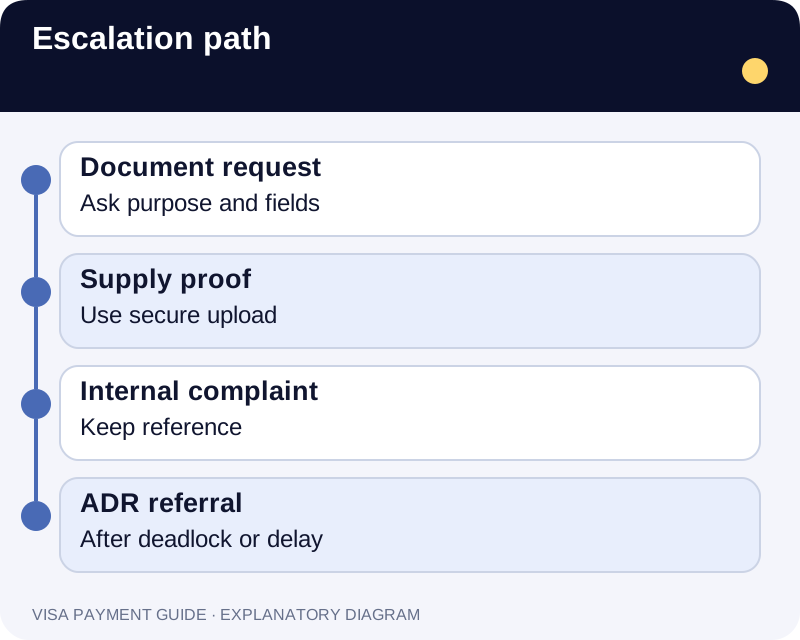
Ask what check is being run and which fields are needed. Send only what answers that question. Use the firm's secure account channel, not ordinary email attachments. Keep a dated copy of every request and reply.
The Gambling Commission requires online operators to verify age and identity before gambling. It says checks cannot be put off until withdrawal when they were reasonably foreseeable earlier. A later request can still be lawful when a new anti-money-laundering or legal duty arises.
Five checks that get confused
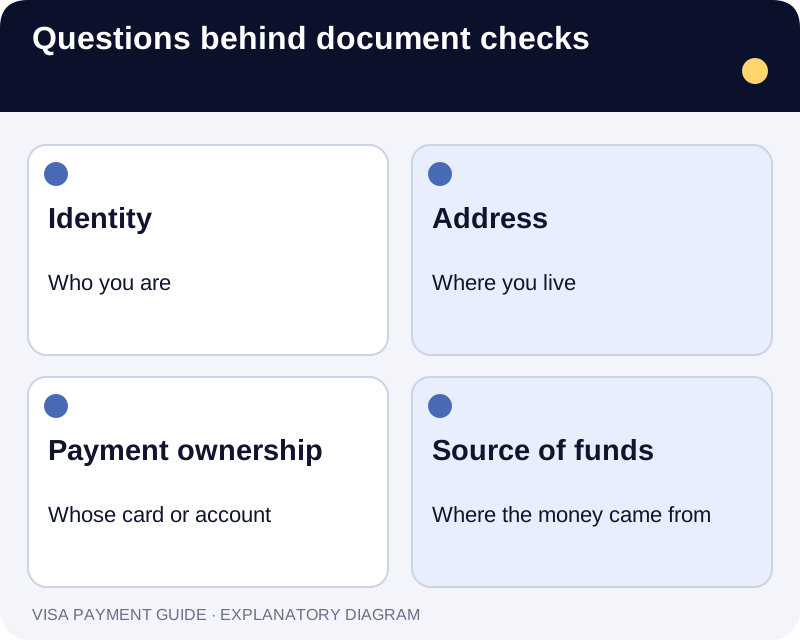
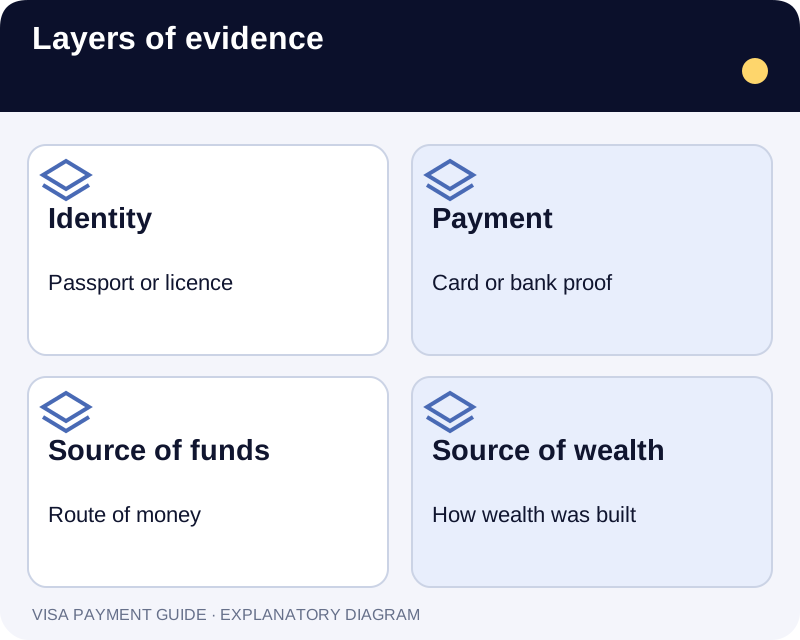
Casinos often use “ID check” as a catch-all. That hides real differences. Each question has its own evidence and legal basis. Knowing which one applies helps you answer without over-sharing.
| Check | Question asked | Typical evidence | Watch for |
|---|---|---|---|
| Age | Are you 18 or over? | Passport, photocard driving licence | Age verification is required before gambling in Great Britain. |
| Identity | Are you the person named on the account? | Photo ID or electronic verification | Name and date of birth must match |
| Address | Where do you live? | Utility bill, bank letter | Date limits vary by firm |
| Payment ownership | Is the card or bank account yours? | Card image, bank statement | Never share PIN or full card number |
| Source of funds | Where did the money you gambled come from? | Payslip, bank statement, sale record | Explain the route of money, not your whole life |
Source of wealth is another distinct question: how you built your overall wealth. It is not the same as source of funds. A casino may ask for both, but should explain which it needs.
What the rules say about timing
The Commission's age and ID verification guide says online operators must verify age and identity before allowing gambling. They cannot defer reasonably foreseeable checks until withdrawal. That protects players from building a balance they cannot access.
The same guide separates identity from later duties. New anti-money-laundering or legal obligations can justify further checks at withdrawal. So a request is not automatically wrong because it arrives late. The question is whether the firm could and should have asked earlier.
The identity verification code guidance sets out how licensees should verify customers. The Commission's common enquiries guide explains that firms should not confiscate a deposit balance merely because identity documents were not supplied.
Great Britain means England, Scotland and Wales. The Gambling Commission regulates most online gambling there. Northern Ireland has different arrangements. Check which regulator applies before you rely on GB guidance.
How to answer a document request
Reply in writing through the account's secure message system. Ask three things: the purpose of the check, the exact fields needed, and the secure upload route. That turns a vague demand into a defined request you can answer safely.
- Ask for purpose in one line: “Please confirm whether this is an identity, address, payment ownership, source of funds or source of wealth check.”
- Offer minimum proof: supply only the fields requested, with sensitive numbers covered where the firm's purpose does not need them.
- Use a secure channel: account upload or verified portal. Avoid ordinary email for passports or bank statements.
- Keep a record: save the request, your reply, upload confirmation and any refusal in one folder.
Do not send your PIN, password or one-time passcode. No lawful check needs them. Do not alter documents. A false or edited document can turn a payment dispute into a fraud issue.
Building a case file that gets answers
A good case file is chronological and short. Start with a one-page summary: account name, date of request, check type, what you sent, what happened. Then attach the documents in date order. This helps a firm's complaints team and, if needed, an alternative dispute resolution (ADR) provider.
| Item | What it shows | Keep as |
|---|---|---|
| Request message | What was asked and when | Saved copy or secure export |
| Your reply | What you supplied and any questions | Dated copy |
| Upload receipt | Proof the firm received it | PDF or image |
| Withdrawal record | Amount, date and status | Account screenshot or statement |
| Complaint reference | The firm's own tracking number | Written note |
Keep the file factual. Write “On 3 March I uploaded a bank statement showing the card ending 1234” rather than “they keep stalling”. Dates and document names carry more weight than adjectives.
If the firm refuses to explain the purpose, ask once more in writing. State that you want to comply but need to know which fields are required. That creates a clear record if you later escalate.
Worked example: a withdrawal held for a source of funds check
The following is illustrative and does not describe a real customer. Suppose a player deposits £800 over two months and requests a £600 withdrawal. The casino asks for a payslip and bank statement. The player sends a payslip. The firm says the check is incomplete.
A useful reply asks which part of the source of funds question remains unanswered. The payslip shows income. The bank statement may show the money moving to the casino. The player can provide a redacted statement covering the relevant period, with unrelated spending hidden if the firm accepts that.
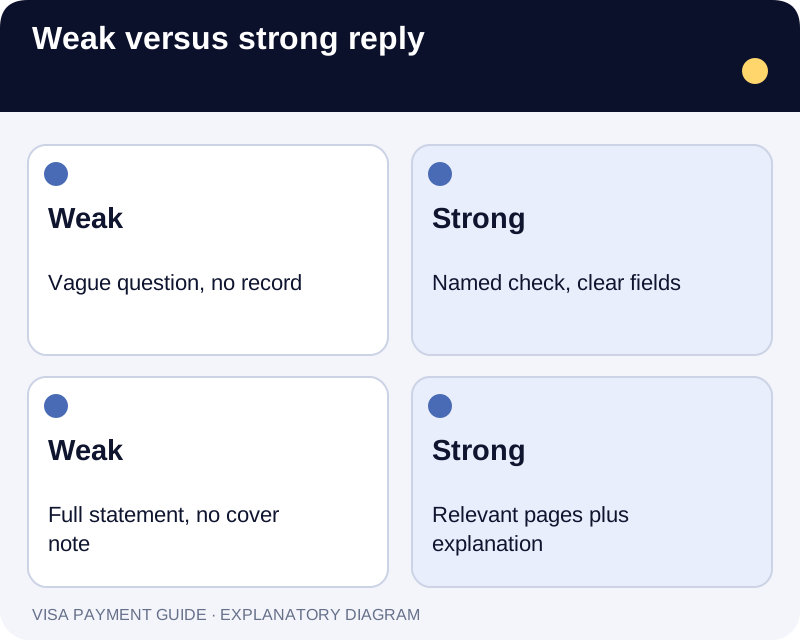
| Point | Weak reply | Strong reply |
|---|---|---|
| Purpose | “Why do you need this?” | “Please confirm this is a source of funds check and list the required fields.” |
| Evidence | Sends full statement with no cover note | Sends relevant pages and a one-line explanation of the money route |
| Record | No copy kept | Keeps request, reply and upload receipt |
The strong reply does not guarantee a faster outcome. It does make the exchange easier to review. If the firm still refuses to pay, the record shows what was asked, what was supplied and what remains disputed.
Privacy and redaction
You can ask why a field is needed and whether a redacted copy will do. Redaction must not defeat the check. Ask which fields the firm needs before hiding them. Covering the name and date of birth needed for an identity check defeats that check.
Use the firm's secure upload. Do not send documents through social media or ordinary email unless the firm provides a verified secure route. Ask how long the firm will keep the copies and whether it will delete them after the check.
For a card payment problem, keep the bank's dispute route separate from the casino complaint. Note the date and amount of each payment. Keep the bank's reference and the casino's complaint reference apart. For more on card disputes, see card payment disputes.
When to escalate
Complain to the firm first. Give it a chance to correct the record. If eight weeks pass without a final response, or you receive a deadlock letter, you may be able to take the case to an ADR provider. The firm should tell you which one it uses.
The Commission does not resolve individual payment disputes. It does collect information about licensees. You can also check a firm's licence with our licence checker. Do this before you rely on its stated regulator.
Escalate when the firm will not say what check applies, will not accept a secure upload, or appears to keep a balance without a lawful basis. Do not escalate simply because a check is inconvenient. Many checks are lawful.
Quick answers
Can a casino ask for ID only when I withdraw?
It should verify age and identity before gambling. A later request can be lawful if a new anti-money-laundering or legal duty arises. Ask which check applies and why it was not done earlier.
What if I do not have a passport or driving licence?
There is no universal list of accepted documents. Ask the firm which alternatives it accepts for the specific check. Do not assume a bank statement proves identity; it may only prove address or funds.
Can the casino keep my deposit if I refuse to send documents?
Commission guidance says a deposit balance should not be confiscated merely because identity documents were not supplied. The firm may still restrict the account while a lawful check is unresolved. Get the reason in writing.
Is a source of funds check the same as source of wealth?
No. Source of funds asks where the money used to gamble came from. Source of wealth asks how your overall wealth was built. A firm should say which one it needs and why.
How do I complain about a document request?
Use the firm's internal complaints process. State the check type, what you sent, and what remains unclear. Keep the reference. If the firm does not resolve it, ask for a deadlock letter and consider ADR.
Sources and review note
We reviewed three public Gambling Commission pages on 14 November 2026: the age and ID verification guide, the identity verification code guidance, and the common enquiries guide. We inspected the stated rules on timing, check types and deposit balances. We did not test any casino, bank or complaints process.
- Age and ID verification guide
- Identity verification code guidance
- Common enquiries from gambling customers
This article gives general information, not legal advice. Rules and firm processes can change. Check the current guidance for your nation of the UK.